A Rolodex, a £9 Savings Plan and a Dodgy Nightclub
- Welcome to the wonderful world of financial services.
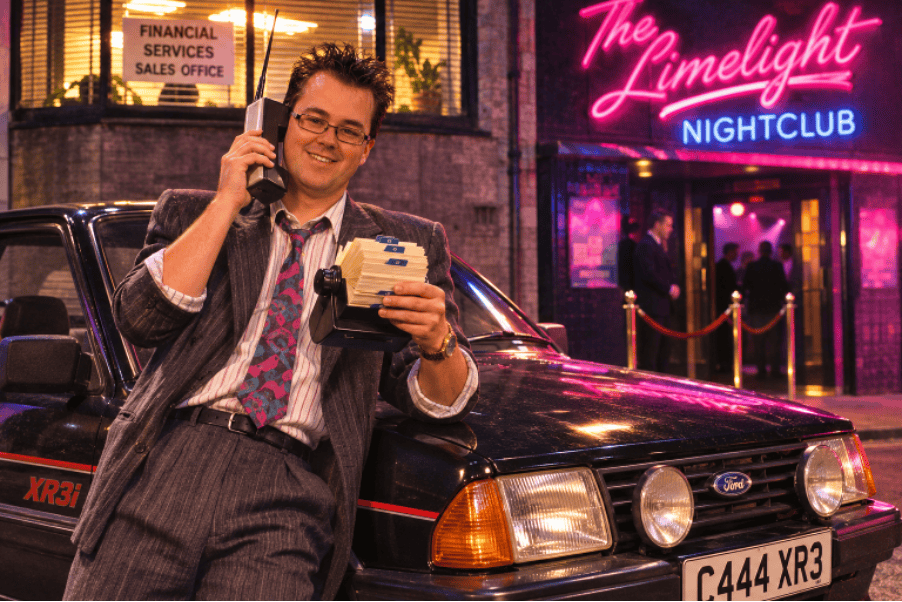
No internet. Massive mobile phones. No LinkedIn. No sophisticated CRM systems.
Just a desk, a telephone, a Rolodex and a monthly sales target.
My job was simple. Pick up the phone, find someone willing to talk to me and sell them something.
The product in question was the Family Assurance Family Bond.
A tax-exempt Friendly Society savings plan costing the princely sum of £9 a month, with a 10-year term.
Sounds harmless enough.
Except, as I remember it, the commission and charges effectively swallowed almost the first FIVE YEARS of contributions.
Five years!
Not exactly a flying start for the client’s savings.
But back then, the industry wasn’t particularly interested in how quickly someone’s money started working for them.
It was interested in sales.
How many calls had you made? How many appointments had you booked? How many policies had you sold?
And, most importantly, had you hit your monthly target? This was the 80’s!
Getting past the gatekeepers
Of course, before you could sell anything, you had to find someone prepared to listen.
That meant hours on the telephone, working through contacts in the Rolodex.
And then there were the secretaries.
Some of them guarded access to their bosses with the determination of a nightclub bouncer.
Which brings me rather neatly to our office.
The office above the nightclub
Our office was situated above a rather dodgy nightclub.
For reasons I never quite understood, the place opened at 12 o’clock in the afternoon.
So while we were upstairs trying to sound professional, selling savings plans over the telephone, we had thumping music coming through the floor.
Not exactly the sophisticated image of financial services!
Mind you, the nightclub did have its uses.
Whenever we hit our monthly sales targets, we didn’t have far to go to celebrate.
Just downstairs.
Looking back, the whole arrangement seems faintly ridiculous.
But the 1980’s was a different world.
Forty years later, what’s changed?
Thankfully, quite a lot.
The industry has moved on from commission-driven sales, at least in mainstream retail investment advice.
We have professional qualifications, greater transparency, better regulation and far more sophisticated ways of helping clients plan their financial futures.
But I sometimes wonder whether we’ve completely shaken off the old sales mentality.
We still see an industry obsessed with products, investment performance, assets under management and business written.
All important commercially, perhaps.
But none of them tells you whether the client is actually better off.
That’s the bit that matters.
Over 40 years, I’ve come to believe that good financial planning has remarkably little to do with financial products.
It’s about understanding people, helping them make good decisions and giving them the confidence to enjoy the money they’ve worked so hard to accumulate.
Sometimes that involves investments.
Sometimes pensions.
Sometimes tax planning.
And sometimes it involves telling someone they can afford to spend more money and enjoy themselves.
Try putting that on a 1986 sales report!
The lesson?
Never confuse selling a financial product with providing financial advice.
They’re two very different things.
And while I wouldn’t swap the experience of those early years, I’m rather glad we’ve moved on.
Although I do occasionally miss the simplicity of the Rolodex.
And the nightclub.
If your financial adviser spends more time talking about products than your plans for life, perhaps it’s time for a different conversation.
At Chatfield Private Client, we believe your money should work for your life, not the other way around.
#40YearsInFinancialServices #FinancialPlanning #WealthManagement #FinancialAdvice